


Your Homeownership Journey Starts Here.
Understanding your mortgage options is one of the first steps toward buying a home. Whether you're a first-time buyer or making your next move, we're here to help you get started with confidence.
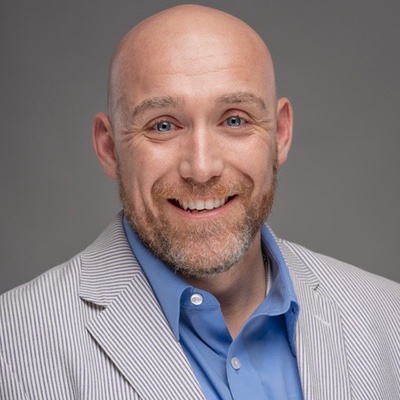
Matt Earley
Mortgage Banker · Atlantic Bay Mortgage Group
For Matt, homeownership is about more than a transaction. He sees it as a life-changing foundation that brings stability, pride and a sense of belonging. That belief shapes how he works with every buyer.
Matt is committed to doing business with integrity, honesty and transparency, because he believes that is the only way to build lasting relationships and trust. He is just as passionate about community: giving back, lifting others up and helping families put down roots in the places they call home. When he isn't helping buyers with financing, you may find him working on a landscaping project, one of his personal passions.
Matt is licensed in North Carolina, so he can help buyers financing homes here along the Brunswick County coast.
- Phone(919) 348-8416
- Emailmattearley@atlanticbay.com
- NMLS #2093275
- Licensed inFL, NC, SC, TN, VA
Contact Matt Call Matt Start Your Mortgage Application
Applications are submitted through Atlantic Bay Mortgage Group's secure online application. Selling The Coast NC never asks for your financial or personal mortgage information on this website. View Matt's official profile.
Understanding the mortgage process
Every loan is a little different, but most home purchases follow the same five steps. Knowing what comes next makes the whole process feel more manageable.
Connect with a lender
Talk through your financial goals, budget and mortgage options.
Get pre-qualified
Receive an initial estimate of what you may be able to borrow.
Get pre-approved
Complete a more detailed financial review to strengthen your position when you shop for a home.
Find your home
Work with your real estate agent to explore properties that fit your needs and budget.
Finalize your mortgage
Complete underwriting, the appraisal and closing requirements.
Pre-qualification
A quick, early estimate of how much you may be able to borrow, usually based on information you share with the lender about your income, debts and savings.
- A helpful starting point for setting a budget
- Typically based on a lighter review of your finances
- Not a commitment to lend
Pre-approval
A more detailed review in which the lender checks your credit and verifies documents such as pay stubs, tax returns and bank statements.
- Gives you a clearer picture of your price range
- A pre-approval letter can strengthen your offer with sellers
- Still subject to final underwriting and appraisal
Neither pre-qualification nor pre-approval guarantees final loan approval. Your loan is approved only after underwriting, which includes verifying your income, credit and assets, and an appraisal of the property.
Explore mortgage options
There is no one-size-fits-all mortgage. Here is a quick overview of the most common home loan types. Matt can help you compare them for your situation.
Conventional loans
Not backed by a government agency and a popular choice for buyers with solid credit. With less than 20% down, private mortgage insurance (PMI) is usually required.
Learn moreFHA loans
Insured by the Federal Housing Administration, with more flexible credit guidelines and down payments as low as 3.5% for qualifying buyers. FHA loans include mortgage insurance premiums.
Learn moreVA loans
A benefit earned through service. Eligible veterans, service members and some surviving spouses may buy with no down payment and no monthly mortgage insurance.
Learn moreUSDA loans
Backed by the U.S. Department of Agriculture for eligible homes in rural and some suburban areas, with no down payment for buyers who meet income and property guidelines.
Learn moreJumbo loans
For loan amounts above the conforming loan limit, such as many waterfront and luxury homes. Jumbo loans usually have stricter credit, down payment and cash-reserve requirements.
Learn moreFirst-time homebuyer programs
Buying your first home? Low down payment loan options and down payment assistance programs may help you buy sooner. Ask Matt which programs you may qualify for.
Learn moreLoan programs are described for general information only. Eligibility, availability, down payment and loan terms depend on your circumstances, the property and lender requirements, and programs may change at any time. Military buyers can also read our Military & VA Homebuyers guide.
Estimate your monthly payment
Try our mortgage calculator to estimate principal and interest, property taxes, insurance and HOA dues for a coastal North Carolina home.
Open the Mortgage CalculatorFrequently asked questions
What's the difference between pre-qualified and pre-approved?
Pre-qualification is an early estimate of what you may be able to borrow, usually based on information you provide about your income, debts and savings. Pre-approval goes further: the lender reviews your credit and verifies documents like pay stubs and bank statements. A pre-approval gives you a more reliable price range and carries more weight with sellers, but neither one guarantees final loan approval.
How much down payment do I need?
It depends on the loan. Some conventional loans allow as little as 3% down for qualifying buyers, FHA loans start at 3.5%, and VA and USDA loans may require no down payment for eligible buyers. Putting 20% down on a conventional loan usually avoids private mortgage insurance. Down payment assistance may also be available. Matt can walk you through the options that fit your situation.
Does getting pre-qualified affect my credit score?
It depends on how the lender handles it. Pre-qualification is often based on information you share or a soft credit check, which does not affect your score. Pre-approval usually includes a hard credit inquiry, which can lower your score slightly for a time. Credit scoring models generally treat several mortgage inquiries within a short shopping period as a single inquiry. Ask Matt what type of credit check his process uses before you start.
What credit score do I need to buy a home?
There is no single minimum. Requirements vary by loan type, lender and your overall financial picture, including income, debts and down payment. Government-backed loans such as FHA can be more flexible than conventional loans. The best way to know where you stand is to talk with a lender, who can review your credit and explain your options.
How long does mortgage pre-approval take?
Timing varies. Much of it depends on how quickly you can provide your documents and how complex your finances are. Having your paperwork ready helps the process move smoothly. Keep in mind that pre-approval letters have an expiration date, so it's a good idea to time yours with your home search.
What documents will I need?
Lenders typically ask for a government-issued photo ID, recent pay stubs, W-2s or 1099s, federal tax returns, recent bank and investment account statements, and information about your current debts. Self-employed buyers, retirees and veterans may be asked for additional documents. Matt will tell you exactly what he needs, and documents are shared through Atlantic Bay's secure process, never through this website.
Can I buy a home if I'm self-employed?
Yes. Self-employed buyers can qualify for a mortgage. The process just looks a little different, because lenders review your business income, usually through tax returns and other financial records, rather than pay stubs. Getting organized early helps. Atlantic Bay has a helpful overview of loans for self-employed homebuyers.
What other costs should I budget for when buying a home?
Beyond your down payment, plan for closing costs, earnest money, a home inspection, the appraisal, moving expenses and ongoing costs like property taxes, homeowners insurance, HOA dues and maintenance. Along the coast, insurance deserves extra attention: wind and hail coverage can add to your premium, and flood insurance may be required for homes in a flood zone. Get insurance quotes on a specific property early in the process.
Ready to Take the First Step Toward Homeownership?
Getting started with the right information can make all the difference. Connect with Matt Earley at Atlantic Bay Mortgage Group to explore your financing options and take the next step with confidence.
Keep exploring
Once you know your budget, start looking at homes and neighborhoods along the coast.
Lender information. Matt Earley, Mortgage Banker, NMLS #2093275, licensed in FL, NC, SC, TN and VA. Atlantic Bay Mortgage Group, L.L.C. NMLS #72043 (nmlsconsumeraccess.org) is an Equal Housing Lender. Located at 600 Lynnhaven Parkway, Suite 100, Virginia Beach, VA 23452. Loan programs may change at any time with or without notice. All loans are subject to income verification, credit approval and property appraisal. This is not a commitment to lend.
About this page. Selling The Coast NC and Joe Huggins, broker with St. James Properties, are not mortgage lenders and do not make loans or loan decisions. Atlantic Bay Mortgage Group is an independent company. You are free to choose any lender. All information on this page is general and educational; payment estimates and program descriptions are not loan offers, rate quotes or guarantees.